Hurricane Isaias:
If you were impacted by the storm, here's
key recovery considerations for the days and weeks ahead
Church Mutual Insurance
Insurance
By Industry
Houses of WorshipNonprofit & Human Services OrganizationsCamps, Sports & Outdoor RecreationEducation & Schools
By Coverage
Specialized CoverageProperty CoverageLiability CoverageWorkers’ Compensation
Resources
Risk Control
View AllChecklists & GuidesSafety ProductsVideos
Articles
View AllCamps, Sports, and Outdoor RecreationEducation and SchoolsHouses of WorshipNonprofit and Human Services
Partner Services
View AllNurse HotlineTelemedicineBackground Checks
Additional Resources
Customer CenterBroker CenterFAQs
Support
Get In Touch
ChatContact Options800-554-2642
Additional Support
Claims CenterPremium AuditPayment CenterFind Your Local RepBroker Center
About
Who We Are
Why Church MutualHistoryLeadershipTestimonialsCM CARES®Newsroom
Careers
Job OpeningsWorking HereCareer AreasDiversity & InclusionBenefitsEarly Career
pay a bill
Pay online:
Make A Payment
Visit our Payment Center for more info. We’ve upgraded our payment system. Read our FAQs for details.
File a Claim
Start Your Claim
Questions? Visit our Claims Center for more info.
Log In
Customer Accounts:
Customer Log In
CREATE ACCOUNT
Broker Accounts:
BROKER LOG IN
CREATE ACCOUNT
search
I’m looking for…
Questions? Check out our FAQs for more info.
Start a Quote
My organization is a
Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.
Start a Quote
US flagChurch Mutual gives backUS flag
Articles
Camps Sports & Outdoor Recreation
Education & Schools
Houses of Worship
Nonprofit & Human Services Organizations
Business Planning
Cybersecurity
Financial Tips
Maintenance
Severe Weather Preparedness
Staff & Volunteer Safety & Management
Articles
Camps Sports & Outdoor Recreation
Education & Schools
Houses of Worship
Nonprofit & Human Services Organizations
Business Planning
Cybersecurity
Financial Tips
Maintenance
Severe Weather Preparedness
Staff & Volunteer Safety & Management
1/23/2025
Information

2025 commercial insurance trends

2025 commercial insurance trends

This article summarizes key findings from the whitepaper "2025 commercial insurance trends and how to navigate them." For comprehensive insights and actionable tips, click here to download the full whitepaper.

The insurance industry has seen a number of changes with increased rates, increased deductibles or even insurability over the past year. This isn’t because insurance companies are taking more than their fair share—it’s because risk levels have gotten substantially higher.

As we begin 2025, it’s important to have a perspective on some of the trends that have caused insurance rates to change so much. Here’s a closer look:

Weather-related disasters and catastrophes

Weather-related disasters and catastrophes

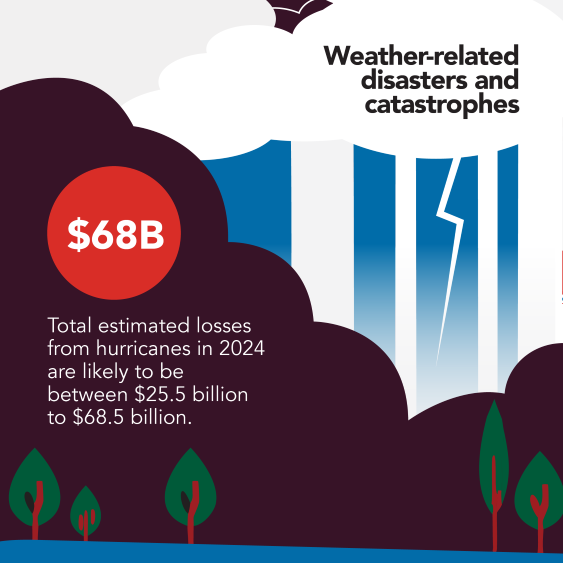
Weather disasters—including hurricanes, wildfires, tornadoes and floods—are currently exceeding expected probability models. This means insurance companies are having to pay much more in claims than they were anticipating, which leads to higher premiums.

While you can’t change the weather, you can prepare for it:
  • Conduct risk assessments and understand the potential impact of weather on your organization.
  • Create a comprehensive emergency plan that will help you minimize disruption during a disaster.
  • Strengthen your building’s existing structure.

Social inflation and nuclear verdicts

Social inflation and nuclear verdicts

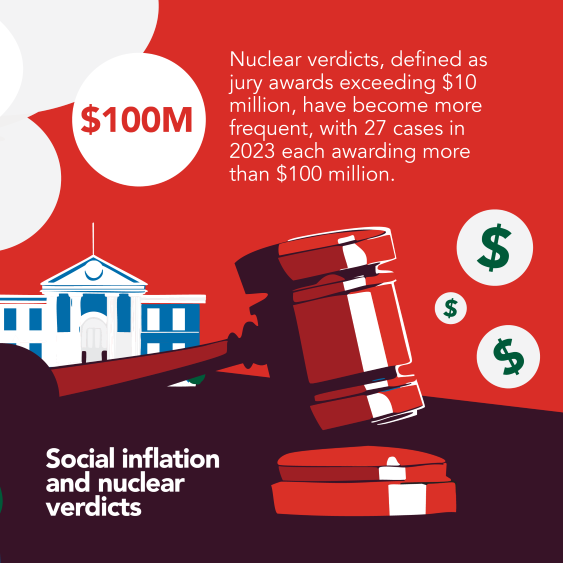
Social inflation is a term that refers to how insurance companies’ claims are increasing above general economic inflation. This occurs when plaintiffs seek—and receive—large amounts for their injuries in lawsuits, sometimes referred to as “nuclear verdicts.”

As an organization, you should adopt risk management strategies that mitigate the financial impact of potential lawsuits. You should:
  • Retain legal counsel to identify potential liabilities and reduce your exposure to risk.
  • Educate your employees and volunteers on ways they can avoid actions that lead to litigation.
  • Adopt multiple risk management strategies throughout your organization.

Increased cost of building supplies

Increased cost of building supplies

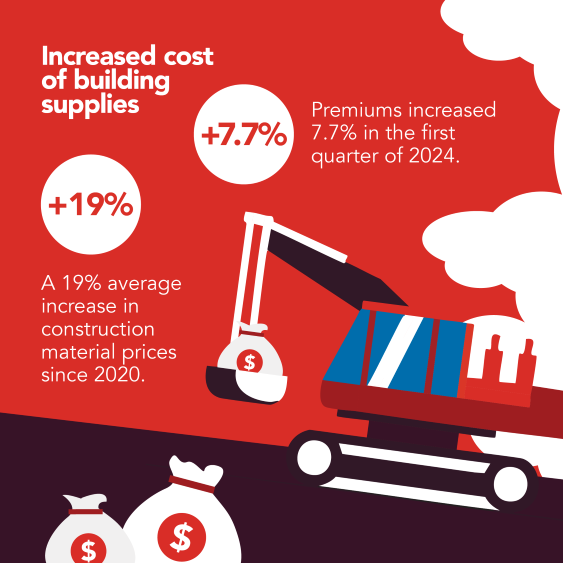
There has been a 19% average increase in building supply costs since 2020, which has led to both increases in overall building costs and in insurance premiums. In particular, prices for materials like steel, concrete and lumber have remained significantly higher than pre-pandemic levels.

To navigate these challenges, you will need to:

  • Plan for higher costs for construction and repair projects in your facility.
  • Seek cost-effective and sustainable building materials, such as recycled or locally sourced products. These may offer both cost savings and environmental benefit.
  • Work with your insurer to adjust your coverage limits. If it costs more to replace your building, you need more insurance coverage. If you don’t regularly review your policy, you may find yourself in for an unpleasant surprise if you file a claim.

Aging infrastructures and insurance problems

Aging infrastructures and insurance problems

If your organization is among the many with an aging building, you know just how frustrating it is when something always seems to be breaking. In particular, many houses of worship are requiring costly updates to remain insurable—80% of religious congregations need maintenance upgrades.

To stay on top of your facility’s needs, you can:

  • Conduct regular inspections to identify and address issues early.
  • Apply for funding opportunities, such as energy efficiency grants, to help pay for necessary upgrades.
  • Prioritize critical repairs that impact insurability and safety.

Cybersecurity risks

Cybersecurity risks

Since the COVID-19 pandemic and shutdown, the public has been clamoring for more online offerings—and organizations are providing them. However, having an online presence puts you more at risk for cybercrime. The projected cost of global cybercrime is expected to reach $12 trillion by 2025.

To safeguard your organization and people’s data, you should:

  • Invest in cybersecurity, such as security software, firewalls and encryption technologies.
  • Train your staff members and volunteers on how to stay safe when working online. In particular, they should know how to recognize phishing attempts and create strong passwords.
  • Adopt a zero-trust approach to enhancing security across your organization. This model requires verification for every access request.

Perhaps most importantly, you can work closely with your insurance company to identify specific, actionable ways to lower your risk and potentially decrease your costs. For more information about how Church Mutual can help you manage risk, visit churchmutual.com/resources.

For a deeper dive into the analysis and strategies presented in this article, click here to download the full whitepaper “2025 commercial insurance trends and how to navigate them.”

Share this article with others:
FacebookLinkedinMailLink
URL copied to clipboard!
Explore more risk resources:
By Category
ArticlesChecklists &GuidesSafety ProductsVideos
By Organization
Camps, Sports & Outdoor RecreationEducation & SchoolsHouses of WorshipNonprofit & Human Service Organizations
By Topic
Buildings & GroundsBusiness PlanningCOVID-19 Response & RecoveryCybersecurityFinancial TipsFire Preparedness & PreventionInjury & Illness PreventionMaintenanceSecurity & Crime PreventionSevere Weather PreparednessSexual Abuse PreventionStaff & Volunteer Safety & ManagementTransportation SafetyTravel

Related Risk Management Articles

view all articles
Ways your nonprofit can lend a hand during the holidaysWays your nonprofit can lend a hand during the holidays

Ways your nonprofit can lend a hand during the holidays

read the article
Arrow
What to know before banning cell phonesWhat to know before banning cell phones

What to know before banning cell phones

read the article
Arrow
Recovering after a tornadoRecovering after a tornado

Recovering after a tornado

read the article
Arrow
Articles
Camps Sports & Outdoor Recreation
Education & Schools
Houses of Worship
Nonprofit & Human Services Organizations
Business Planning
Cybersecurity
Financial Tips
Maintenance
Severe Weather Preparedness
Staff & Volunteer Safety & Management

2025 commercial insurance trends

This article summarizes key findings from the whitepaper "2025 commercial insurance trends and how to navigate them." For comprehensive insights and actionable tips, click here to download the full whitepaper.

The insurance industry has seen a number of changes with increased rates, increased deductibles or even insurability over the past year. This isn’t because insurance companies are taking more than their fair share—it’s because risk levels have gotten substantially higher.

As we begin 2025, it’s important to have a perspective on some of the trends that have caused insurance rates to change so much. Here’s a closer look:


Weather-related disasters and catastrophes

Weather-related disasters and catastrophes

Weather disasters—including hurricanes, wildfires, tornadoes and floods—are currently exceeding expected probability models. This means insurance companies are having to pay much more in claims than they were anticipating, which leads to higher premiums.

While you can’t change the weather, you can prepare for it:

  • Conduct risk assessments and understand the potential impact of weather on your organization.
  • Create a comprehensive emergency plan that will help you minimize disruption during a disaster.
  • Strengthen your building’s existing structure.

Social inflation and nuclear verdicts

Social inflation and nuclear verdicts

Social inflation is a term that refers to how insurance companies’ claims are increasing above general economic inflation. This occurs when plaintiffs seek—and receive—large amounts for their injuries in lawsuits, sometimes referred to as “nuclear verdicts.”

As an organization, you should adopt risk management strategies that mitigate the financial impact of potential lawsuits. You should:

  • Retain legal counsel to identify potential liabilities and reduce your exposure to risk.
  • Educate your employees and volunteers on ways they can avoid actions that lead to litigation.
  • Adopt multiple risk management strategies throughout your organization.

Increased cost of building supplies

Increased cost of building supplies

There has been a 19% average increase in building supply costs since 2020, which has led to both increases in overall building costs and in insurance premiums. In particular, prices for materials like steel, concrete and lumber have remained significantly higher than pre-pandemic levels.

To navigate these challenges, you will need to:

  • Plan for higher costs for construction and repair projects in your facility.
  • Seek cost-effective and sustainable building materials, such as recycled or locally sourced products. These may offer both cost savings and environmental benefit.
  • Work with your insurer to adjust your coverage limits. If it costs more to replace your building, you need more insurance coverage. If you don’t regularly review your policy, you may find yourself in for an unpleasant surprise if you file a claim.

Aging infrastructures and insurance problems

Aging infrastructures and insurance problems

If your organization is among the many with an aging building, you know just how frustrating it is when something always seems to be breaking. In particular, many houses of worship are requiring costly updates to remain insurable—80% of religious congregations need maintenance upgrades.

To stay on top of your facility’s needs, you can:

  • Conduct regular inspections to identify and address issues early.
  • Apply for funding opportunities, such as energy efficiency grants, to help pay for necessary upgrades.
  • Prioritize critical repairs that impact insurability and safety.

Cybersecurity risks

Cybersecurity risks

Since the COVID-19 pandemic and shutdown, the public has been clamoring for more online offerings—and organizations are providing them. However, having an online presence puts you more at risk for cybercrime. The projected cost of global cybercrime is expected to reach $12 trillion by 2025.

To safeguard your organization and people’s data, you should:

  • Invest in cybersecurity, such as security software, firewalls and encryption technologies.
  • Train your staff members and volunteers on how to stay safe when working online. In particular, they should know how to recognize phishing attempts and create strong passwords.
  • Adopt a zero-trust approach to enhancing security across your organization. This model requires verification for every access request.

Perhaps most importantly, you can work closely with your insurance company to identify specific, actionable ways to lower your risk and potentially decrease your costs. For more information about how Church Mutual can help you manage risk, visit churchmutual.com/resources.

For a deeper dive into the analysis and strategies presented in this article, click here to download the full whitepaper “2025 commercial insurance trends and how to navigate them.”

Related Risk Management Videos

view all videos
CybersecurityCybersecurity

Cybersecurity

Watch the Video
Arrow
Webinar: Financial FreedomWebinar: Financial Freedom

Webinar: Financial Freedom

Watch the Video
Arrow
Webinar: Faith + FitnessWebinar: Faith + Fitness

Webinar: Faith + Fitness

Watch the Video
Arrow
Articles
Information
Safety Products are NO COST for Church Mutual customers.

2025 commercial insurance trends

first-time enrollment
order additional devices
Order In Portal
2025 commercial insurance trends

Related Risk Management Safety Products

view all safety products
Swim BandsSwim Bands

Swim Bands

Learn More & Order
Arrow
CM Wildfire Solutions™CM Wildfire Solutions™

CM Wildfire Solutions™

Learn More & Order
Arrow
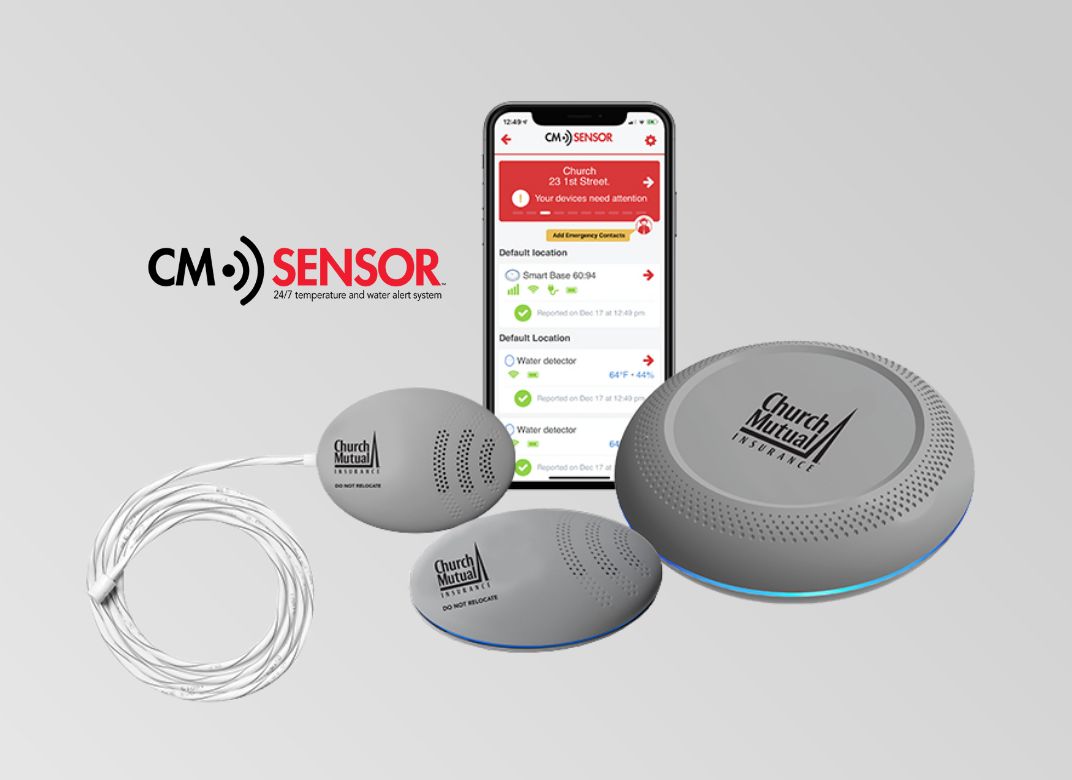
CM Sensor® 24/7 Temperature and Water Alert SystemCM Sensor® 24/7 Temperature and Water Alert System

CM Sensor® 24/7 Temperature and Water Alert System

Learn More & Order
Arrow
Articles
Camps Sports & Outdoor Recreation
Education & Schools
Houses of Worship
Nonprofit & Human Services Organizations
Business Planning
Cybersecurity
Financial Tips
Maintenance
Severe Weather Preparedness
Staff & Volunteer Safety & Management

2025 commercial insurance trends

download now
open in a new tab
2025 commercial insurance trends

This article summarizes key findings from the whitepaper "2025 commercial insurance trends and how to navigate them." For comprehensive insights and actionable tips, click here to download the full whitepaper.

The insurance industry has seen a number of changes with increased rates, increased deductibles or even insurability over the past year. This isn’t because insurance companies are taking more than their fair share—it’s because risk levels have gotten substantially higher.

As we begin 2025, it’s important to have a perspective on some of the trends that have caused insurance rates to change so much. Here’s a closer look:


Weather-related disasters and catastrophes

Weather-related disasters and catastrophes

Weather disasters—including hurricanes, wildfires, tornadoes and floods—are currently exceeding expected probability models. This means insurance companies are having to pay much more in claims than they were anticipating, which leads to higher premiums.

While you can’t change the weather, you can prepare for it:

  • Conduct risk assessments and understand the potential impact of weather on your organization.
  • Create a comprehensive emergency plan that will help you minimize disruption during a disaster.
  • Strengthen your building’s existing structure.

Social inflation and nuclear verdicts

Social inflation and nuclear verdicts

Social inflation is a term that refers to how insurance companies’ claims are increasing above general economic inflation. This occurs when plaintiffs seek—and receive—large amounts for their injuries in lawsuits, sometimes referred to as “nuclear verdicts.”

As an organization, you should adopt risk management strategies that mitigate the financial impact of potential lawsuits. You should:

  • Retain legal counsel to identify potential liabilities and reduce your exposure to risk.
  • Educate your employees and volunteers on ways they can avoid actions that lead to litigation.
  • Adopt multiple risk management strategies throughout your organization.

Increased cost of building supplies

Increased cost of building supplies

There has been a 19% average increase in building supply costs since 2020, which has led to both increases in overall building costs and in insurance premiums. In particular, prices for materials like steel, concrete and lumber have remained significantly higher than pre-pandemic levels.

To navigate these challenges, you will need to:

  • Plan for higher costs for construction and repair projects in your facility.
  • Seek cost-effective and sustainable building materials, such as recycled or locally sourced products. These may offer both cost savings and environmental benefit.
  • Work with your insurer to adjust your coverage limits. If it costs more to replace your building, you need more insurance coverage. If you don’t regularly review your policy, you may find yourself in for an unpleasant surprise if you file a claim.

Aging infrastructures and insurance problems

Aging infrastructures and insurance problems

If your organization is among the many with an aging building, you know just how frustrating it is when something always seems to be breaking. In particular, many houses of worship are requiring costly updates to remain insurable—80% of religious congregations need maintenance upgrades.

To stay on top of your facility’s needs, you can:

  • Conduct regular inspections to identify and address issues early.
  • Apply for funding opportunities, such as energy efficiency grants, to help pay for necessary upgrades.
  • Prioritize critical repairs that impact insurability and safety.

Cybersecurity risks

Cybersecurity risks

Since the COVID-19 pandemic and shutdown, the public has been clamoring for more online offerings—and organizations are providing them. However, having an online presence puts you more at risk for cybercrime. The projected cost of global cybercrime is expected to reach $12 trillion by 2025.

To safeguard your organization and people’s data, you should:

  • Invest in cybersecurity, such as security software, firewalls and encryption technologies.
  • Train your staff members and volunteers on how to stay safe when working online. In particular, they should know how to recognize phishing attempts and create strong passwords.
  • Adopt a zero-trust approach to enhancing security across your organization. This model requires verification for every access request.

Perhaps most importantly, you can work closely with your insurance company to identify specific, actionable ways to lower your risk and potentially decrease your costs. For more information about how Church Mutual can help you manage risk, visit churchmutual.com/resources.

For a deeper dive into the analysis and strategies presented in this article, click here to download the full whitepaper “2025 commercial insurance trends and how to navigate them.”

download now
open in a new tab

Related Risk Management Checklists & Guides

view all checklists & guides
Verifications and References from Trusted Employees2025 commercial insurance trends

Verifications and References from Trusted Employees

Get the Guide
Arrow
Should Your Church Accommodate Known Sex Offenders?2025 commercial insurance trends

Should Your Church Accommodate Known Sex Offenders?

Get the Guide
Arrow
Tornado Tabletop Exercise: Practice Your Organization's Plan2025 commercial insurance trends

Tornado Tabletop Exercise: Practice Your Organization's Plan

Get the Guide
Arrow
Church Mutual Insurance
Facebook
LinkedIn
Youtube
Instagram
800-554-2642
Quick Links
Request a QuotePay a BillFile a ClaimFind Your Local Rep
Get Answers
Contact UsClaims CenterPayment CenterCustomer CenterBroker CenterNewsroom
Careers
Job OpeningsWorking HereCareer AreasDiversity & InclusionBenefitsEarly Career
Site Map
|
Consent Preferences
|
Legal & Privacy Policy

Church Mutual Insurance Company, S.I. (a stock insurer) | P.O. Box 357 | 3000 Schuster Lane | Merrill, WI 54452-0357 | Telephone (800) 554-2642 or (715) 536-5577
© 2026 Church Mutual Insurance Company, S.I. All rights reserved. Protecting the Greater Good is a registered trademark of Church Mutual Insurance Company, S.I.

¹ Church Mutual is a stock insurer whose policyholders are members of the parent mutual holding company formed on 1/1/20. S.I. = a stock insurer.